When most people think about high-yield dividend stocks, Goldman Sachs probably isn’t the first name that comes to mind. The yield sits around 1.9% — modest by any measure. But look closer, and a very different story emerges. The GS Dividend Date 2026 has grown at an average of 21% per year over the past decade, the payout ratio is a conservative 29%, and Q2 2026 earnings hit a record $20.34 billion in revenue. For investors who prioritize dividend growth over raw yield, GS deserves serious attention.
This article breaks down exactly what the Goldman Sachs dividend looks like today, why the low yield doesn’t tell the whole story, and how it might or might not fit your retirement income strategy.
What Is the GS Dividend Right Now?
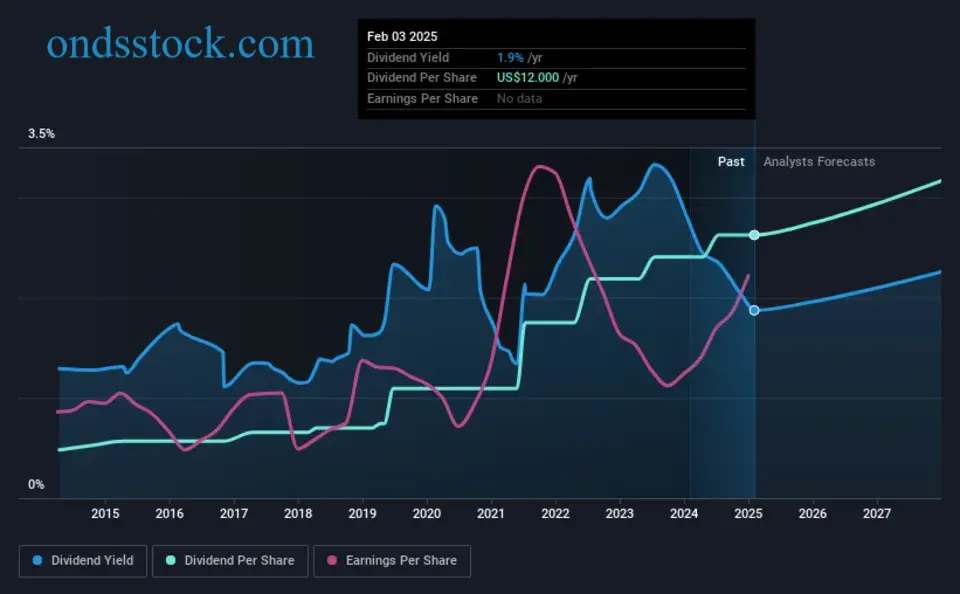
Short answer: Goldman Sachs pays a quarterly dividend of $5.00 per share, with a trailing annual yield of approximately 1.92% as of September 2026.
Here are the key numbers at a glance:
| Metric | Value (September 2026) |
|---|---|
| Quarterly Dividend Per Share | $5.00 |
| Annualized Dividend Per Share | $20.00 |
| Dividend Yield | ~1.92% |
| Payout Ratio | ~29% |
| Ex-Dividend Date | September 1, 2026 |
| Payment Date | September 29, 2026 |
| Consecutive Years of Increases | 15 years |
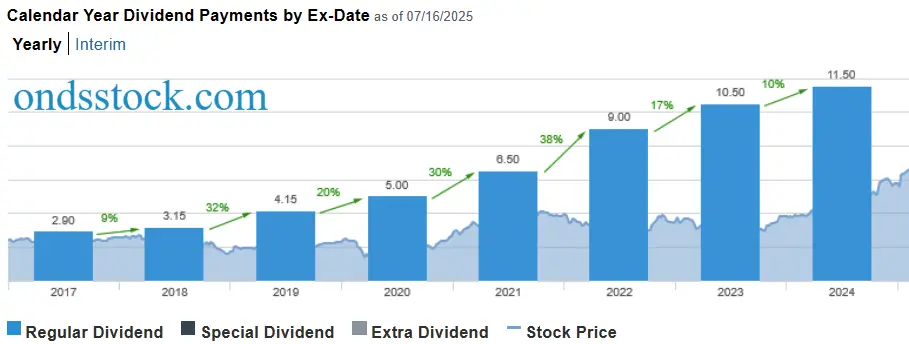
| 10-Year Average Annual Dividend Growth | ~21% |
Goldman Sachs raised its quarterly dividend from $4.50 to $5.00 following its record Q2 2026 earnings report — an 11% increase in a single quarter. That kind of aggressive growth is rare among large-cap financial stocks and reflects a company that is generating significantly more cash than it needs to sustain its current payout.
Is the GS Dividend Sustainable?
Short answer: Yes, by most conventional metrics, the Goldman Sachs dividend looks well-supported and has substantial room to keep growing.
The most straightforward way to evaluate dividend sustainability is the payout ratio — the percentage of earnings a company distributes as dividends. Goldman Sachs currently pays out roughly 29% of its earnings, which is quite conservative. Most analysts consider anything below 60% to be healthy for a mature company, and below 40% to be genuinely comfortable.
That matters for a few reasons. First, it means Goldman Sachs retains the vast majority of its profits to reinvest in operations, make acquisitions, and buy back shares. Second, it creates a substantial buffer. Even if earnings declined meaningfully — say 30% or 40% — the dividend would still be covered without cutting into reserves. Third, it sets the stage for continued dividend growth: as earnings expand, there’s room to raise the payout well ahead of inflation without straining the balance sheet.
The Q1 2026 earnings report showed diluted EPS of $17.55 — the second highest in Goldman Sachs history — and Q2 2026 delivered EPS of $20.98, up 92% year-over-year. These are not the numbers of a company struggling to fund its dividend. EPS for the trailing twelve months through June 2026 stands at $65.63, which means the $20.00 annual dividend represents roughly 30 cents of every dollar earned.
The Yield vs. Growth Trade-Off
Here’s where things get interesting for income-focused investors. A 1.92% yield isn’t going to cover your monthly expenses in retirement on its own. If you need $5,000 per month from dividends, you’d need over $3 million invested in GS at today’s yield. That’s not a realistic strategy for most people.
But dividend yield is only one side of the equation. The other side is dividend growth rate.
Consider this: if you bought GS shares ten years ago when the annual payout was $2.20 per share, you’d be receiving $20.00 per share today on that original investment. That’s a 9x increase in income from the same number of shares. Investors who purchased at that time and have held through are now receiving a yield on cost that looks very different from the current 1.92%.
This is the fundamental appeal of dividend growth investing. You’re not optimizing for today’s income — you’re building a reliable income stream that grows meaningfully over time, ideally faster than inflation. GS has achieved exactly that over the past decade. simplywall.st
GS Dividend vs. High-Yield Alternatives
Some investors searching for dividend income get drawn to higher-yielding options like preferred shares or high-yield dividend stocks that pay 7% or more. Those yields are real, but the trade-offs are significant.
| Feature | GS Common Stock | Typical High-Yield Preferred |
|---|---|---|
| Current Yield | ~1.92% | 6% – 9.5% |
| Dividend Growth | ~21% avg. annually (10 yr) | Typically fixed or minimal |
| Capital Appreciation Potential | High | Low to none |
| Dividend Sustainability | Strong (29% payout ratio) | Varies; often more fragile |
| Principal Preservation Risk | Market-dependent | Interest rate sensitivity |
Preferred shares — such as those offered by Citibank’s Series N or other bank-issued preferred securities — pay fixed dividends that can look attractive on paper. However, they don’t grow. The income you receive in year one is the income you’ll receive in year ten. Meanwhile, inflation erodes the real value of those fixed payments every year.
With GS common stock, you accept a lower starting yield in exchange for income that has historically grown faster than inflation and much faster than fixed alternatives. For someone building a retirement portfolio with a 20 to 30-year time horizon, that trade-off often makes more sense than it first appears.
Goldman Sachs’ Financial Strength Behind the Dividend
The GS dividend doesn’t exist in isolation — it’s backed by one of the most consistently profitable financial institutions in the world. Here’s the business context that makes the payout credible.
In Q2 2026, Goldman Sachs reported:
- Revenue: $20.34 billion (up 39% year-over-year)
- Net Income: $6.40 billion (up 85% year-over-year)
- Return on Equity (ROE): 23.5%
- Assets Under Supervision: $4.04 trillion (record high)
- Global Banking & Markets Revenue: $15.52 billion (up 53%)
These results reflect a firm that has effectively shed its consumer banking experiment and returned to its core strengths — investment banking, trading, and wealth management. Advisory revenue in Q1 2026 rose 89% year-over-year. Equities revenue hit records. The firm’s backlog for M&A advisory is reportedly at a five-year high.
The P/E ratio as of late September 2026 sits around 14.6x — only slightly above Goldman Sachs’ own 10-year historical average of roughly 12.5x. That’s not stretched by historical standards, especially given the earnings trajectory. EPS has grown 26.5% year-over-year in 2025 and is tracking even faster in 2026.
How the GS Dividend Fits a Retirement Strategy
This is where you need to be honest with yourself about what you actually need from your portfolio.
If you’re in or near retirement and you need consistent retirement income starting today, a 1.92% yield from GS probably won’t carry the load on its own. You’d need to pair it with higher-yielding instruments, Social Security income, or other income sources.
However, if you’re planning several years ahead — building toward retirement rather than drawing from it right now — a position in GS could serve a different function. Think of it as an income engine that starts small and accelerates. The dividend has grown 17.84% annually over the past three years. At that rate, a $10,000 investment generating roughly $192 per year in dividends today could be generating significantly more within a decade — without you adding a single dollar to the position.
There’s also the capital appreciation angle. GS stock has moved considerably over the past year, and while past performance never guarantees future returns, the underlying business is generating record earnings. For retirement investors, total return — dividends plus price appreciation — matters too, especially during the accumulation phase.
For income-focused investors who do want to include GS in a retirement portfolio, a practical approach is to treat it as a growth-oriented dividend position rather than a yield play. Pair it with higher-yielding, more stable income sources for current cash flow, and let the GS position compound over time.
Risks Worth Knowing Before You Invest
No honest discussion of the GS dividend is complete without addressing the risks.
Market sensitivity. Goldman Sachs’ revenue is heavily tied to capital markets activity. When deal-making slows, trading volumes fall, or market volatility spikes in the wrong direction, earnings can drop sharply. The 2022 earnings decline illustrated this clearly. A prolonged downturn could pressure the dividend, even if the payout ratio looks comfortable today.
Yield relative to alternatives. As interest rates remain elevated, investors can access Treasury bonds and high-grade corporate bonds yielding 4% to 5% or more with significantly less volatility. For pure income generation without growth requirements, GS doesn’t compete on raw yield.
Stock price volatility. GS traded between roughly $705 and $1,154 over the past 52 weeks — a wide range. Retirees who need to draw on principal in down years face real sequence-of-returns risk. This reinforces the idea that GS works better as part of a diversified income strategy than as a standalone retirement income vehicle.
Dividend growth isn’t guaranteed. The 15-year streak of increases is impressive, but it’s a function of earnings growth. If EPS contracts materially, dividend growth could stall or reverse. The conservative payout ratio provides a cushion, but not immunity.
Quick Summary: What You Need to Know
- The GS dividend currently pays $5.00 per quarter, or $20.00 annualized, yielding approximately 1.92%.
- The payout ratio is around 29%, making the dividend well-covered and sustainable under current earnings.
- Goldman Sachs has raised its dividend for 15 consecutive years, growing the payout at an average of 21% per year over the past decade.
- Q2 2026 earnings were record-setting, with revenue of $20.34 billion and net income of $6.40 billion.
- GS works better as a dividend growth position than a high-yield income stock for immediate retirement cash flow.
- The stock carries meaningful market risk tied to capital markets cycles and macroeconomic conditions.
Frequently Asked Questions
Will GS stock split in 2026?
As of September 2026, Goldman Sachs has not announced any stock split. GS has never undergone a stock split in its public history since its 1999 IPO. With shares trading around $960, a split would make the stock more accessible to retail investors, but the company has shown no indication it intends to pursue one. There is no confirmed plan for a GS stock split in 2026.
What is the 15-minute rule at Goldman Sachs?
The 15-minute rule at Goldman Sachs is an internal cultural standard — not a formal regulation — that reflects the firm’s expectations around responsiveness and professional urgency. Employees are generally expected to respond to calls and messages from senior colleagues or clients within roughly 15 minutes during business hours. It’s part of the firm’s high-performance culture and reflects the fast-moving nature of investment banking and trading environments. This rule has nothing to do with trading or dividend investing — it’s purely an internal professional standard.
Is GS a good dividend stock?
It depends on what you’re looking for. If you want a high current yield, GS is not the right pick — its 1.92% yield is well below the Financial Services sector average of around 2.69%. But if you want a financially strong company with a long track record of raising its dividend aggressively — 21% annually over ten years — then GS is genuinely impressive. It’s best suited for dividend growth investors who are accumulating income over time, not those who need maximum cash flow right now.
What is the 25% dividend rule?
The 25% dividend rule is an informal investing guideline suggesting that a company’s payout ratio should not exceed 25% of its earnings, ensuring the dividend remains sustainable and the company retains enough profit for reinvestment. Goldman Sachs’ current payout ratio of approximately 29% sits just above this threshold — still very conservative by any standard, and well within the range most analysts consider healthy and sustainable. Some variations of this rule apply to specific sectors or use free cash flow rather than net earnings as the denominator.
Read More…