Introduction
VTEB stock is attracting attention from investors who want to explore bond market opportunities, generate regular income, and potentially reduce their federal income tax burden. The Vanguard Tax-Exempt Bond ETF offers exposure to investment-grade municipal bonds issued by U.S. states, local governments, and public agencies. Unlike shares of an individual company, this exchange-traded fund invests in a diversified collection of bonds that generate interest income.
As of October 14, 2026, the provided market data lists VTEB at $47.54, with an intraday range of $47.36 to $47.56. However, its price is only one part of the investment picture. Investors should also examine its distribution history, yield, expense ratio, interest-rate sensitivity, and potential tax benefits before making a decision.
Whether you are building an income-focused portfolio or comparing municipal bond ETFs, understanding how VTEB works can help you make a more informed choice. This guide explores its features, benefits, risks, and alternatives to help you determine whether it deserves a place in your investment strategy.
What Is VTEB Stock?
VTEB is the ticker symbol for the Vanguard Tax-Exempt Bond ETF, which trades on NYSE Arca. The fund seeks to track the performance of a broad index representing the investment-grade, tax-exempt U.S. municipal bond market. Its underlying investments include bonds issued by state and local governments and certain public agencies to finance infrastructure, education, transportation, and other public projects.
Although investors commonly search for VTEB stock, it is important to understand that this investment is an ETF rather than an individual company’s stock. You are purchasing shares in a fund that holds numerous bonds, not ownership in a single business. This structure provides diversified municipal bond exposure through one exchange-traded investment, although diversification does not eliminate market risk or guarantee positive returns.
VTEB Stock Price and Market Performance
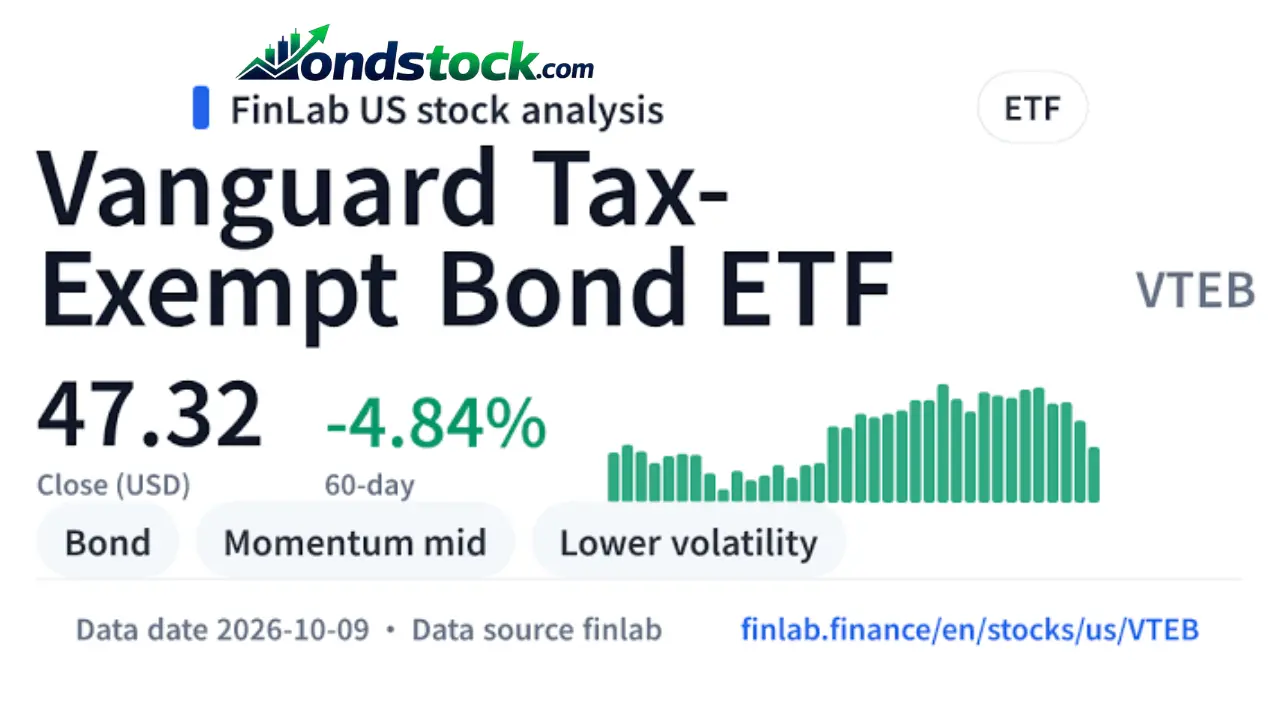
According to the market information provided for October 14, 2026, VTEB was trading at $47.54. Its reported daily change was down $0.11, or approximately 0.23%, while its 52-week trading range extended from $46.87 to $51.18. These figures provide a snapshot of recent price behavior, but they should not be interpreted as a complete measure of the fund’s investment performance.
Investors should evaluate total returns alongside the market price. Total return accounts for both changes in the share price and distributions received over a specified period, assuming the relevant distribution treatment is included. Because bond prices respond to interest rates, inflation expectations, credit conditions, and investor demand, VTEB can lose value even when its underlying bonds continue generating interest income. digital.fidelity.com
What Influences the VTEB Price?
Several factors can influence the ETF’s market price and net asset value:
- Interest rates: Rising rates can reduce the market value of existing bonds, while falling rates can support bond prices.
- Municipal credit quality: Changes in the perceived financial strength of bond issuers can affect valuations.
- Inflation expectations: Higher expected inflation may put upward pressure on interest rates.
- Market demand: Investor interest in tax-exempt income can influence municipal bond prices.
- Portfolio characteristics: Bond maturity, duration, and credit exposure affect sensitivity to changing market conditions.
Reviewing these factors alongside historical returns provides a more useful picture than looking at the latest quote alone.
VTEB Dividend and Distribution Yield
The VTEB dividend is more accurately described as a fund distribution, primarily reflecting income generated by its underlying municipal bonds. Unlike a company that distributes profits to shareholders, a bond ETF generally passes along income earned from interest payments, after applicable fund expenses and other adjustments. Distribution amounts can vary, so investors should consult Vanguard’s official fund information for the latest announcements and payment history.
The VTEB dividend yield is another important consideration for income-focused investors. Yield expresses distributions in relation to a specified share price or follows another defined calculation, depending on the measure being reported. It can change when distributions change or the ETF’s market price moves. A higher quoted yield does not necessarily indicate a better investment because it may accompany greater risk or reflect a different yield calculation.
How to Evaluate VTEB Dividend History
Historical distributions can help investors understand how the fund has generated income over time. However, past payments do not guarantee future distributions, and dividend history alone does not reveal whether an investment has delivered positive total returns.
When reviewing distribution records, focus on:
- Previous distribution amounts and payment dates.
- The fund’s latest published yield measures.
- Changes in the market price and net asset value.
- The relationship between income distributions and total returns.
- The difference between historical payments and future estimates.
Investors should also distinguish between SEC yield, distribution yield, and total return. These measures answer different questions and should not be compared as though they were interchangeable.
VTEB Expense Ratio and Investment Costs
The expense ratio measures the annual operating expenses of a fund as a percentage of its assets. The supplied research identifies VTEB’s net expense ratio as 0.03%, although investors should verify the latest figure on Vanguard’s official website before relying on it. A low expense ratio can help preserve more of a fund’s gross investment return over time, making costs an important consideration when comparing similar ETFs.
The expense ratio is not the only cost to consider. Brokerage commissions, bid-ask spreads, and trading conditions may also affect the amount an investor pays. Even a low-cost ETF can experience losses when market conditions deteriorate. Comparing VTEB with competing municipal bond funds requires examining fees alongside yield, duration, credit quality, diversification, and overall performance.
Is VTEB a Good Investment in 2026?
Whether VTEB is worth buying depends on your financial objectives, tax situation, investment horizon, and tolerance for fluctuations in bond prices. Its focus on investment-grade municipal bonds may appeal to investors seeking diversified fixed-income exposure and potentially federally tax-exempt interest. However, the fund is not a savings account, and its share price can decline when interest rates rise or credit conditions weaken.
Before investing, examine the current yield, duration, expense ratio, holdings, and historical total returns. Your tax bracket also matters because the value of tax-exempt income varies between investors. Someone in a higher federal income tax bracket may benefit differently from municipal bonds than someone in a lower bracket. Consider the fund as part of your overall portfolio rather than evaluating it in isolation.
Potential Benefits of VTEB
VTEB offers several features that may appeal to investors who understand municipal bond risks.
- Diversification across numerous municipal bond issuers.
- Potential income that is exempt from U.S. federal income tax.
- Convenient access to the municipal bond market through an ETF.
- A relatively low reported expense ratio of 0.03%, subject to verification.
- The potential to complement stocks and other fixed-income investments.
These benefits may make the fund useful for some income-oriented portfolios, but they do not guarantee capital preservation or superior returns.
Risks of Investing in VTEB
Every bond fund carries risks, and tax advantages do not remove them. Interest-rate risk is especially important because the market value of existing bonds generally falls when comparable interest rates rise. Credit risk also matters because municipal issuers can face financial difficulties, potentially affecting bond valuations or payments.
Other considerations include inflation risk, liquidity conditions, and changes in tax rules. Although interest from qualifying municipal bonds is generally exempt from federal income tax, some distributions may receive different treatment, and state or local taxes can apply. Investors should review the fund’s official tax information and consider professional advice when their circumstances require it.
VTEB vs. MUB vs. BND
Investors researching VTEB often compare it with the iShares National Muni Bond ETF (MUB) and the Vanguard Total Bond Market ETF (BND). While all three provide bond exposure, their investment objectives and tax characteristics differ. VTEB and MUB focus on municipal bonds, whereas BND offers broader exposure to the U.S. taxable investment-grade bond market.
| Feature | VTEB | MUB | BND |
|---|---|---|---|
| Fund provider | Vanguard | iShares | Vanguard |
| Main exposure | Municipal bonds | Municipal bonds | Broad U.S. bond market |
| Income tax treatment | Qualifying interest generally federally tax-exempt | Qualifying interest generally federally tax-exempt | Income generally includes federally taxable interest |
| Expense ratio | 0.03%, based on supplied research | Verify current figure | Verify current figure |
| Yield | Check latest official data | Check latest official data | Check latest official data |
| Main consideration | Tax-exempt income and municipal bond risk | Tax-exempt income and municipal bond risk | Broader fixed-income diversification |
VTEB may be attractive to investors seeking low-cost municipal bond exposure, while MUB offers another way to access that market. BND may suit investors who prefer broader bond diversification. The better choice depends on your after-tax income, risk tolerance, portfolio needs, and current fund characteristics rather than the headline yield alone.
How to Add VTEB to a Diversified Portfolio
VTEB may complement a portfolio containing stocks, cash, and other bonds. Its municipal bond holdings can provide a different source of income from equity dividends, potentially helping investors diversify across asset classes. Nevertheless, the fund remains exposed to interest-rate and credit risks, so its value may decline during periods of market stress.
Investors who also hold the Vanguard High Dividend Yield ETF (VYM) should recognize that the two funds serve different purposes. VYM invests in dividend-paying stocks, which offer equity growth potential but carry stock market risk. VTEB focuses on municipal bonds and potential tax-exempt interest income. Combining them can diversify income sources, but it does not eliminate losses or guarantee a stable overall return.
Before choosing an allocation, consider your time horizon, liquidity needs, tax circumstances, and preferred balance between growth and income. Revisit your portfolio periodically to ensure that the allocation remains consistent with your objectives.
How to Buy VTEB in 2026
Buying VTEB generally involves opening or using a brokerage account that provides access to NYSE Arca-listed ETFs. Search for the ticker symbol VTEB, confirm that the fund is the Vanguard Tax-Exempt Bond ETF, and review the available market information before placing an order.
Investors should understand the difference between market orders and limit orders. A market order seeks immediate execution at available prices, while a limit order specifies the maximum price you are willing to pay when buying. Review the bid-ask spread, trading costs, fund prospectus, and current holdings before committing money. The fund’s market price and distributions can change, and no particular purchase price guarantees a profit.
VTEB Stock Outlook for 2026 and Beyond
The future performance of VTEB will depend partly on interest-rate movements, municipal bond market conditions, issuer credit quality, and investor demand for tax-exempt income. If interest rates decline, existing bonds may gain value, although the outcome will depend on other market factors. Conversely, rising rates may place downward pressure on bond prices even when the fund continues collecting interest.
Rather than relying on a specific price forecast, investors should monitor changes in duration, yield, expenses, and portfolio composition. Consider how the fund might perform under different economic scenarios and whether its income characteristics fit your financial goals. Historical results can provide context, but they cannot predict future returns.
Conclusion: Is VTEB Worth Buying in 2026?
VTEB offers investors a convenient way to access a diversified portfolio of investment-grade U.S. municipal bonds. Its low reported expense ratio and potential federal tax advantages may appeal to investors seeking fixed-income exposure and regular income distributions. However, the ETF’s market price can fluctuate, distributions can change, and tax benefits depend on individual circumstances.
Before investing, compare its current yield, distribution history, duration, expenses, and risks with alternatives such as MUB and BND. The most suitable choice is the one that aligns with your income needs, tax position, risk tolerance, and long-term investment plan. Verify all market figures through official fund sources before making a decision.
Frequently Asked Questions
What is VTEB stock?
VTEB is the ticker symbol for the Vanguard Tax-Exempt Bond ETF, which invests primarily in investment-grade U.S. municipal bonds.
What was the VTEB stock price on October 14, 2026?
The supplied market data reported a price of $47.54 at 12:10 p.m. EDT on October 14, 2026.
Does VTEB pay monthly dividends?
VTEB makes income distributions, and investors should check Vanguard’s official distribution schedule to confirm the latest frequency and payment details.
What is the VTEB dividend yield?
The yield changes with the fund’s market price and distributions, so consult Vanguard’s latest published yield data for the current figure.
What is the VTEB expense ratio?
The supplied research lists a net expense ratio of 0.03%, but investors should verify the current figure on Vanguard’s official website.
Is VTEB exempt from federal income tax?
Interest from qualifying municipal bonds is generally exempt from federal income tax, although some distributions and individual tax circumstances may receive different treatment.
Is VTEB better than MUB or BND?
VTEB and MUB focus on municipal bonds, while BND provides broader bond exposure; the most suitable option depends on taxes, costs, and investment goals.
Can VTEB lose value?
Yes, VTEB can decline in value because of rising interest rates, credit concerns, market conditions, or other factors affecting municipal bonds.
Also Read…